Why the Rental Desk in an Orange Beach Condo Tower Can Change How You Finance It
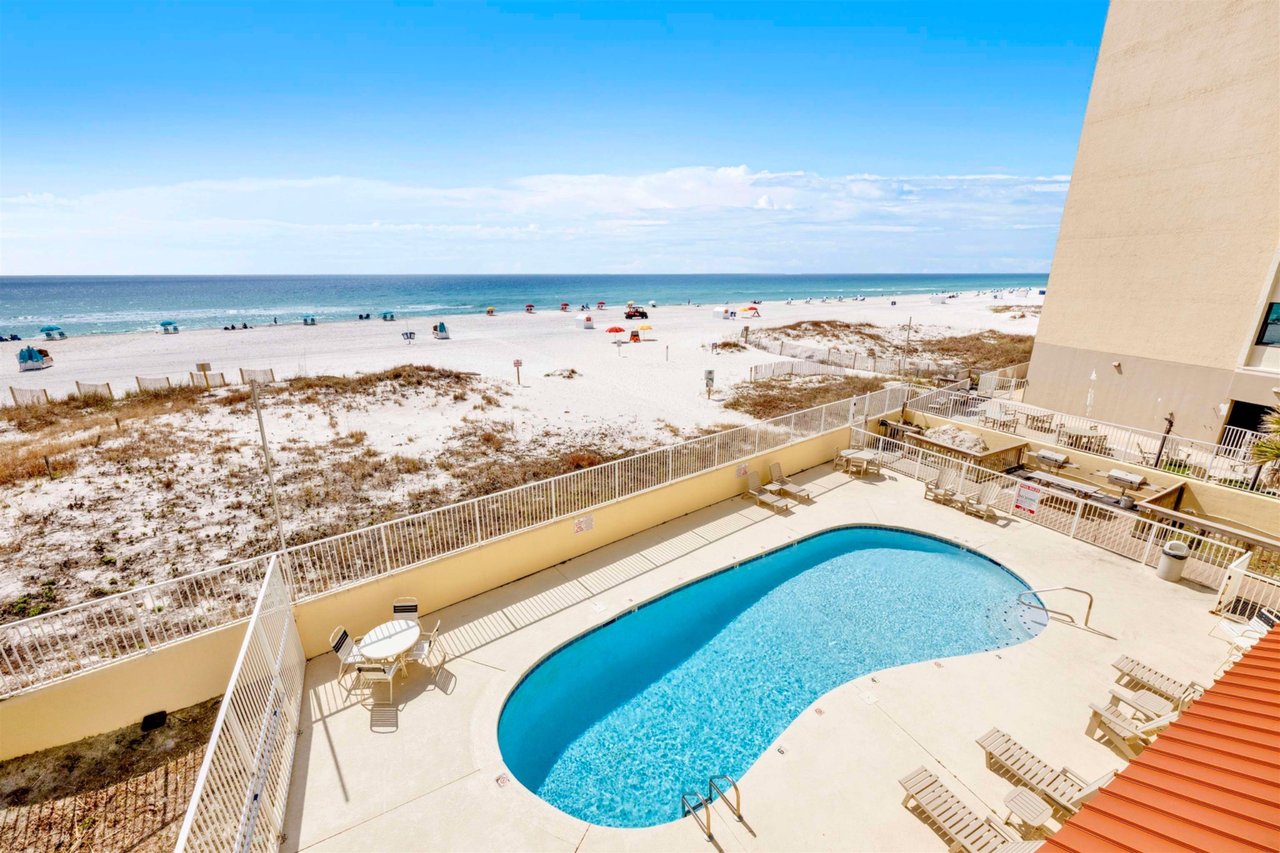
Whether a Gulf-front condo in Orange Beach can carry a conventional mortgage depends heavily on how the whole building handles vacation rentals. The view, the floor plan and the asking price come later. Freddie Mac's current guide lists specific operating details, such as who collects the lodging tax, who staffs the front desk and who manages the rentals, that can turn a condominium into what the agency calls a Condominium Hotel or transient housing. If a project falls in that category, Freddie Mac generally won't buy loans on its units. The exceptions are loans delivered through its Exempt From Review path or in projects with a Project Certified status from its Project Assessment Request review.
On the coast, that review result belongs to the property just as much as its square footage does. It decides whether a buyer needs 5 percent down or 25 percent, a standard rate or a premium one, a mainstream lender or a specialty lender. It also decides how many buyers can make an offer at all.
Underwriters review the project at the time they underwrite the loan. Fannie Mae says that if a project fails its Selling Guide requirements, loans on its units can't be sold to Fannie Mae "until the underlying reasons are resolved." The rental questions are written out in detail. Under Freddie Mac Guide Section 5701.3, a project counts as transient housing if any one of these is true:
A separate list covers the Condominium Hotel label itself. It applies to projects licensed as a hotel or motel, projects with mandatory rental pooling or blackout dates on owner use, and projects where owners share revenue with the HOA or its contracted rental operator. Freddie Mac also names daily cleaning, porters, room service, central telephone service and central key systems as common red flags.
Fannie Mae's summary is shorter. Among the project types it says it can't finance "as a matter of law" are those that "operate as a hotel/motel, or manage daily or short-term rentals, even if the units are individually owned."
A tower can allow short-term rentals and still get through the review. Freddie Mac's guide says so directly:
"Condominium Projects with short-term rentals, personalized services and/or centralized systems may be eligible if the Seller fully analyzes all the characteristics of the project and related information to determine if the project is not a Condominium Hotel or transient housing as described above."
"Seller" in that sentence means the lender selling the loan to Freddie Mac. Two towers next to each other on Perdido Beach Boulevard can both have renters on their balconies every week and still get different answers. The difference comes from who runs the rentals and where the money goes.
Lodging tax is the trigger most likely to come up locally, because every rental in town carries it. The City of Orange Beach puts the total lodging tax at 16 percent: 10 percent city, 4 percent state and 2 percent Baldwin County. The Alabama Department of Revenue's September 2026 rate report shows the same city and county rates.
Who collects that tax matters to an underwriter. Under Alabama Rule 810-6-5-.22.01, an accommodations intermediary generally collects and remits state and parallel local lodging taxes on transactions from January 1, 2025. A written agreement can make the property owner the remitting party instead. Freddie Mac's trigger is narrower than "someone collects the tax." It asks whether the HOA or its management agent does it as the rental operator or licensed agent. So a tower where independent rental companies handle bookings and taxes looks different on paper from one where the association's own management company does.
The city puts the license obligation on the owner. Orange Beach says the owner, not the rental management company, is responsible for getting the City business license to rent a condo or house. Licenses expire December 31 and can be renewed through January 31 without penalty. A buyer planning to rent out the unit should add that to the first-year calendar, whichever financing path the building allows.
A condo that doesn't meet agency standards is called non-warrantable. Gulf Coast Bank & Trust lists projects that allow short-term rentals among the usual causes and says non-warrantable condos are common in Gulf Coast beach communities with heavy vacation-rental activity, including along the Alabama coast. The usual fix is a portfolio loan, which the lender keeps instead of selling. The bank says these loans may require a lower debt-to-income ratio, a higher credit score, a larger down payment and slightly higher rates.
Lenders publish general ranges, and they vary:
| Financing path | Published guidance |
|---|---|
| DSCR investor loan, Gulf Shores and Orange Beach | 20% to 25% down, some programs at 15% |
| DSCR loan on a property classified as a condotel, Alabama | Up to 75% loan-to-value on purchase, so 25% down |
| Non-warrantable condo loan, national guidance | 20% to 25% or more down, roughly 0.5 to 1.5 points above a comparable conventional condo rate |
These are program parameters, not rate quotes, and individual lenders apply their own overlays. On a $700,000 unit, the gap between a conventional second-home loan and a 25 percent-down condotel loan can mean six figures more cash at closing. Some buyers can't cover that, and some decide to pay cash instead.
Each financing hurdle removes some potential buyers, and fewer buyers usually means a longer wait for the right one. Baldwin REALTORS reported this for August 2026, using its MLS area breakdown:
| August 2026 | Coastal Condos | Coastal Homes |
|---|---|---|
| Properties sold | 81 | 78 |
| Average sales price | $697,805 | $910,922 |
| Average days on market | 129 | 84 |
| Avg. price change from August 2025 | Down 7.17% | Down 1.48% |
Coastal condos took about six and a half weeks longer to sell than coastal homes, even though homes cost more on average. The countywide condo picture from the Alabama Center for Real Estate points the same way. In July 2026, Baldwin County had 1,059 active condo listings, or 11.0 months of supply at the current sales pace. ACRE treats 6 months as the point where buyers and sellers have roughly equal leverage. Condos sold that month averaged 119 days on market, 46 days slower than in July 2025.
These figures don't prove that financing causes the gap. Insurance costs, rental performance and seasonality all affect condo demand. Baldwin REALTORS also cautions that new MLS area definitions and its platform change can distort comparisons with earlier reports. Still, in a market with 11 months of supply, a unit that only a smaller group of buyers can finance competes from behind.
Fannie Mae says it doesn't publish or disclose project eligibility decisions to anyone other than lenders, HOAs, their management companies and authorized advisors. Buyers with questions are pointed to the HOA or their lender. In practice, a buyer often learns how a building is classified only after making an offer, once the lender starts its review. In a slow month, a financing surprise at that point can cost a seller the deal.
An Orange Beach condo seller can answer most of the lender's questions before the listing goes live by gathering:
Fannie Mae says HOAs can send updated documentation once issues are fixed, and that it has updated the status of more than 2,000 projects since 2022 after receiving it. A board that understands which triggers apply to its building has something it can act on.
Not by itself under Freddie Mac's wording. The trigger depends on whether the HOA pays for or earns revenue from desk services, whether desk staff also serve as vacation rental employees, and whether rental payments run through the desk. Market-rate rent paid by a third party for desk space is specifically excluded.
Fannie Mae reported that 3.6 percent of projects had an ineligible status as of August 2025, with insufficient master insurance and critical repairs as the top two reasons. That is a national figure, not a Gulf Coast estimate.
Freddie Mac's Section 5701.3 text shows an effective date of May 6, 2026. Fannie Mae's Selling Guide published September 2, 2026 lists its Ineligible Projects section as revised August 5, 2026. Lenders apply their own policies on top of both, so the lender's review of a specific building is the final word.
This article is general information, not lending advice. Before you make an offer on a Gulf-front unit, or before you list one, Leigh McPherson and the team can help you pull together the building's rental structure, management agreement and insurance details, so the financing question is settled early instead of surfacing a week before closing.
Stay up to date on the latest real estate trends.
What Goes Into Making a Competitive Offer in Orange Beach’s Coastal Market.
Luxury Market Insights
Coastal Entryway Design Ideas to Make Your Orange Beach Home Feel Like a Retreat.
Luxury
Investor Intelligence
What Sold
It is an honor to not only help dozens of clients buy or sell their properties but also see so many of their stories play out and get to be a part of writing a chapter. We strive to always take care of our clients with thorough communication, strategic negotiation skills, local contacts for specialized professions, area knowledge, as well as a touch of style and grace.